Retail and commercial banks
Customer onboarding, deposits, branch operations, lending and service management with bank-owned financial controls.
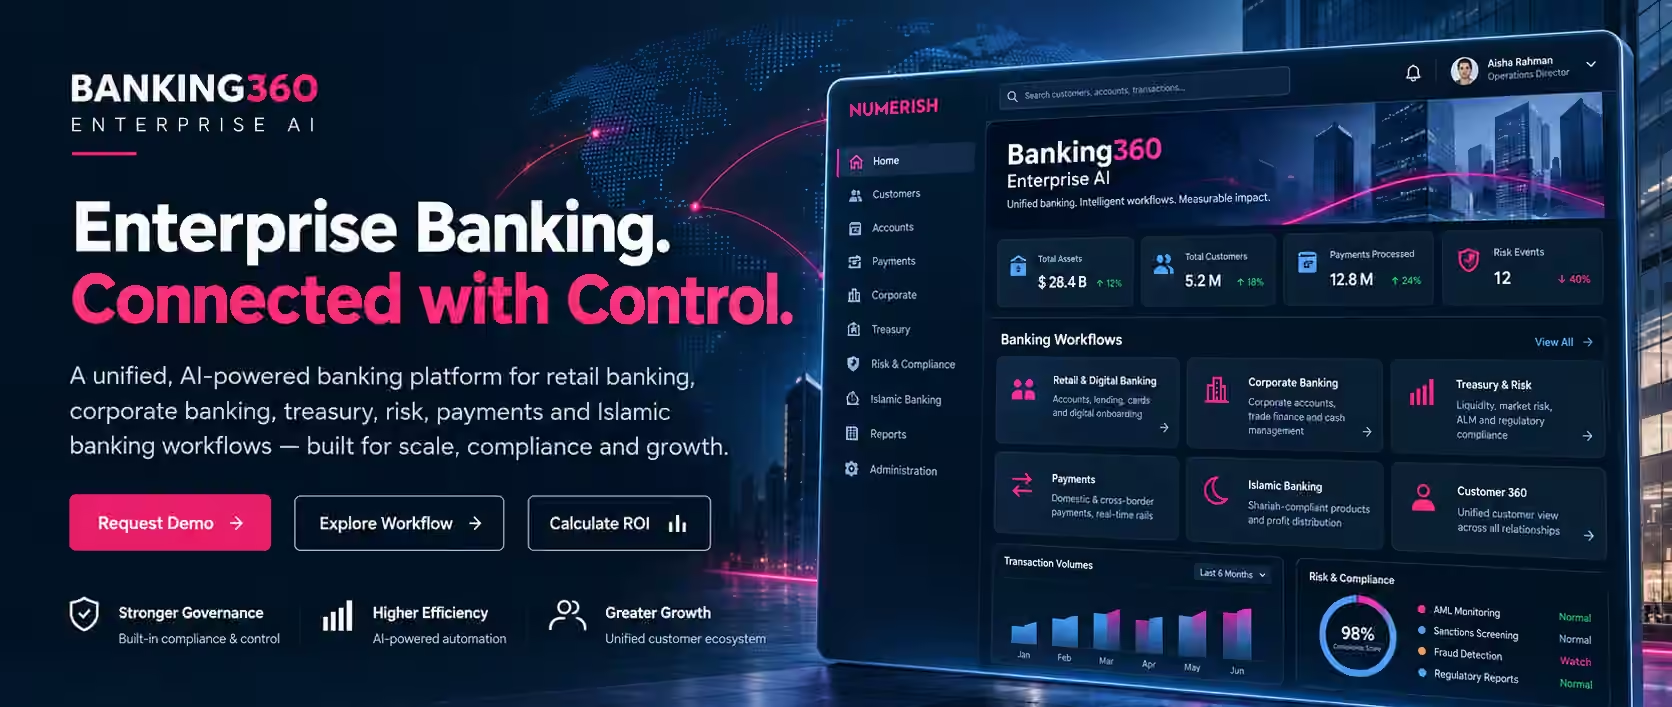
Governed retail, corporate, digital, treasury, risk, payments and Islamic banking workflows for institutional evaluation.
CONNECTED BANKING OPERATIONS
Coordinate customer onboarding, deposits, payments, lending, corporate treasury, financial crime and Islamic finance through bank-authorized workflows, role ownership and audit trails.
Choose the operating model that reflects your legal institution, products, customer groups and country requirements. A subscription does not grant deposit-taking or payment-network authorisation.
Customer onboarding, deposits, branch operations, lending and service management with bank-owned financial controls.
Secure digital experiences, API-led customer journeys, consent and controlled integrations with core financial systems.
Credit origination, servicing, collections, risk and regulated reporting according to local institution eligibility.
Branch governance, multi-currency servicing, corporate relationships, cash and treasury oversight.
Entity-separated operations, group controls, advanced liquidity, finance and cross-border readiness.
Contract-specific financing, asset evidence and investment pools requiring Sharia Supervisory Board oversight.
Manage interconnected workflows and evidence across the institution, keeping products, service, risk and financial control in their rightful roles.
Customer onboarding, identity controls, current and savings account structures, statement journeys and service-case handling.
Legal entities, authorized mandates, multicurrency views, corporate payments, virtual collections and cash-management control paths.
Payment instruction governance, ISO 20022/SWIFT-oriented integration designs, exception handling and controlled card/merchant connections.
Origination, credit review, collateral, facilities, supply-chain and trade-finance workflow evidence with separate approval authority.
Liquidity and source-backed cash-flow observation, ECL scenario analysis, technical treasury controls and governed model validation.
Independent maker/checker decisions, fraud investigation, sanctions/KYC control pathways, role-scoped access and evidence registers.
Murabaha, Ijara, Mudaraba, Musharaka, Wakala, Qard, Salam and Istisna technical journeys with bank- and Sharia-specific evidence controls.
Role-aware workbenches, guided next steps, customer experience interfaces, governed AI evaluation and operational assurance.
Banking360 supports institution-specific workflow evaluation and connected operational control. Live network settlement, customer money, legally executed financing, production banking AI models and independent regulatory certification require original institutional commissioning and evidence. Availability varies by module, bank and jurisdiction.
Select an operating model to explore how source evidence, responsibilities and independent decisions connect across the banking lifecycle.
A connected flow that keeps verified identity, product authority, transaction rights and customer records under the correct bank's control.
Explore the operational sequence from institution admission to customer services, lending, payments, treasury, Islamic banking, resilience and governed AI. Each example is subject to real bank and provider commissioning.
Loading institutional workflow descriptions…
Select a banking journey to review accountable steps, specialist controls and the intended handoff.
These are illustrative workflows and integration designs. Descriptions do not certify actual customer fund processing, regulatory acceptance, provider connectivity or bank account finality.
Support Islamic finance programmes without treating an ordinary interest-bearing lending workflow as an Islamic contract. Contract-specific evidence, approval order and accounting boundaries matter.
Banking360 includes technical workflows for Murabaha, Ijara, Mudaraba, Musharaka, Wakala, Qard, Salam and Istisna, alongside evaluation workflows for investment accounts, profit pools, asset lifecycles, capital loss and Zakat/purification controls.
Banking360 coordinates financial-institution workflows without duplicating the authoritative responsibilities of ERP360's specialist modules.
Banking360Institution-scoped banking operating layerBank-owned staff, customer admission, role evidence and recent MFA.
Payment-network source contracts, provider approval and settlement evidence.
Bank-source ledger handoff, reconciliation and financial reporting under separate authorities.
Case progression, control mapping, approvals and bank-specific evidence.
Mandates, legal documents, immutable records and controlled retention.
Purpose-bound event delivery, integration contracts and operational monitoring.
Wealth360 remains the specialist owner for private-wealth portfolios, advisory, investment mandates, custody and trust/escrow workflows. Securities360 retains securities-specific operations. Banking360 supplies the banking relationship, operating-account context, controlled handoffs and bank authorization.
Govern financial activity through identity boundaries, least privilege, independent reviews and source-backed evidence, with clear external commissioning gates.
Separate institutional staff permissions, recent MFA and tenant isolation. Enterprise portal membership does not grant bank-account authority.
Role separation for product staging, independent review, financial controls and regulated decisions.
Original ledger records, three-way reconciliation candidates, bounded calculations and exception evidence paths.
ISO, Basel/BCBS, IFRS, ISO 20022, AAOIFI and IFSB research references. Country-specific rules and certification require independent validation.
Designed around controlled releases, HSM/SOC, backup/recovery and independent security acceptance; certification cannot be inferred from design.
Human-owned model validation, explainability, risk review and evidence before financial AI can influence regulated decisions.
From the bank administrator and maker to Risk, Compliance, Operations, Auditor and authorized customer, guided tasks explain prerequisites, role ownership, next action and supporting evidence.
Quantify manual review, duplicated handling and analyst time that a connected banking workflow may address. Use your institution's real operating baseline before making a business case.
You control every assumption. No external banking performance benchmark, live financial result or guaranteed saving is implied.
We scope the banking operating model with your institution: legal authority, data residency, identity, original ledger ownership, approved integrations and independently witnessed resilience.
Jurisdiction and permitted products, bank-owned legal approval, verified staff, MFA and independent checker.
Bank-scoped PostgreSQL, residency, key custody, least privilege, audit and controlled data movement.
Source mapping, parallel-run reconciliation, ECL, signed adjustments, rollback and verified financial reporting.
Bank-owned scheme contracts, integration testing, delivery receipts, independent DR and signed release decisions.
Banking360 supports institutional evaluations across different operating scales. Pricing, data residency, permitted products, custom deployment and entitlements require a reviewed PricingHub quotation and regulatory commissioning.
Evaluate workflows, security boundaries and integrations against test data.
Configure smaller institutional products, customer journeys and risk controls.
Evaluate digital customer experiences and bank-controlled onboarding.
Assess branches, corporate operations, cross-entity controls and reporting.
Coordinate specialist banking lines, treasury, risk and integration governance.
Design country-aware operating models and institution-led global controls.
Indicative evaluation focus, not a contracted inclusion or approved price book. Actual modules, scale, service levels and operational rights require an approved quotation and commissioning.
| Plan | Typical institution | Operating focus | Specialist options | Commercial basis |
|---|---|---|---|---|
| Sandbox | Evaluation team | Non-posting workflows, controlled test data | Technical demonstrations | Private proposal, no live financial service |
| Microfinance | Eligible specialist credit institution | Lending, servicing, collections and customer controls | Fraud, credit data, branch channels | Institution-specific legal and capacity scope |
| Digital Banking | Licensed digital-first institution | Onboarding, digital customer journeys and APIs | Partner integrations, white-label, digital channels | Bank-specific feature and infrastructure quote |
| Regional Banking | Multi-branch regional institution | Retail, corporate, branch and treasury controls | Trade, treasury, agent/ATM and support | Branches, staff and country scope contracted |
| Enterprise Banking | Large institutional bank | Corporate credit, trade, ALM, risk and finance | Advanced analytics, HSM/DR, managed integrations | Institutional architecture and legal scope quote |
| Global Banking | Multi-entity international group | Country-specific governance and cross-entity oversight | Multi-jurisdiction, high availability, specialist systems | Independently contracted entity and region terms |
The public website does not publish unapproved banking price books or enable a self-service regulated-bank checkout. PricingHub, bank legal terms, provider contracts and applicable licensing decisions control subscription eligibility.
Distinguishing product architecture, source workflows, external approvals and institution-led commissioning is part of a responsible banking software evaluation.
Banking360 is a dedicated banking software add-on with bank-specific accounts, institutional workspaces, products, financial-control and integration workflows. It is distinct from Accounting360's enterprise finance operations. Production bank processing is subject to genuine bank approvals, provider connectivity and independent financial acceptance.
Banking360's design targets responsive, accessible and role-aware experiences, informed by WCAG 2.2 Level AA and OWASP ASVS. Its governance mapping considers ISO/IEC 27001 (information security), ISO/IEC 27701 (privacy), ISO 22301 (business continuity) and ISO/IEC 42001 (AI management); applicable privacy laws such as GDPR and POPIA; and relevant banking requirements including ISO 20022, Basel/BCBS guidance, IFRS and PCI DSS. Islamic banking workflows additionally reference applicable AAOIFI and IFSB standards. These are design targets and framework mappings, not claims of universal compliance or independent certification. Production approval requires institution- and jurisdiction-specific assessments, tested accessibility and security, financial validation and signed independent acceptance evidence.
The platform includes payment-network metadata, technical source contracts and regulated approval pathways. Live network access requires each institution's separate agreements, technical certification and signed transaction or settlement acceptance. No universal connection or certified live settlement is implied by this website.
Banking360 includes contract-specific technical paths for Murabaha, Ijara, Mudaraba, Musharaka, Wakala, Qard, Salam and Istisna, plus source-account and investment-pool scenarios. Independent Sharia Supervisory Board approval, actual asset titles, customer investment funds and applicable accounting treatments require further institution-led commissioning.
No. Specialist wealth mandates, discretionary/advisory portfolios, custody, trusts and escrow remain under Wealth360; securities-specific operations remain with Securities360. Banking360 provides the banking operating relationship, institutional account context and governed integration handoffs.
It can be scoped around your institution's original financial source. Integrating with an existing core or replacing it requires a bank-approved source mapping, migration proof, parallel-run reconciliation, independent financial acceptance and operational certification. No universal core replacement is claimed.
Each bank's legal authority, approved deployment and country policy determine residency, permitted customer data, key custody and banking roles. Numerish platform administrator rights do not authorize transactions or bank account access.
No. Network, issuer, processor and bank scheme connections depend on original contracts, technical certification, secure key custody, provider receipts and the financial service scope actually commissioned.
Quotes distinguish licensed institution scope, products and modules, users, branches, active accounts, transactions, API volume, infrastructure, security and recovery, implementation/migration, support, third-party charges, usage credits and taxes. Prices are reviewed independently before being offered.
The proposed bank programme includes a governed import and reconciliation process, disaster recovery and PITR drills, independent replay checks, export/exit terms and original-bank custody. Any target RTO, RPO or service level is specified and independently qualified in the final contract.
Request an institutional demonstration and operating-model assessment. Any subscription, customer-data processing, financial-network connection, banking deployment or pricing approval is governed by PricingHub, licensed bank personnel and the applicable legal and independent acceptance process.
See how Banking360 connects your customer, product, banking-risk, financial-control and specialist software journeys. Start with an institutional demonstration and a scoped implementation discussion.